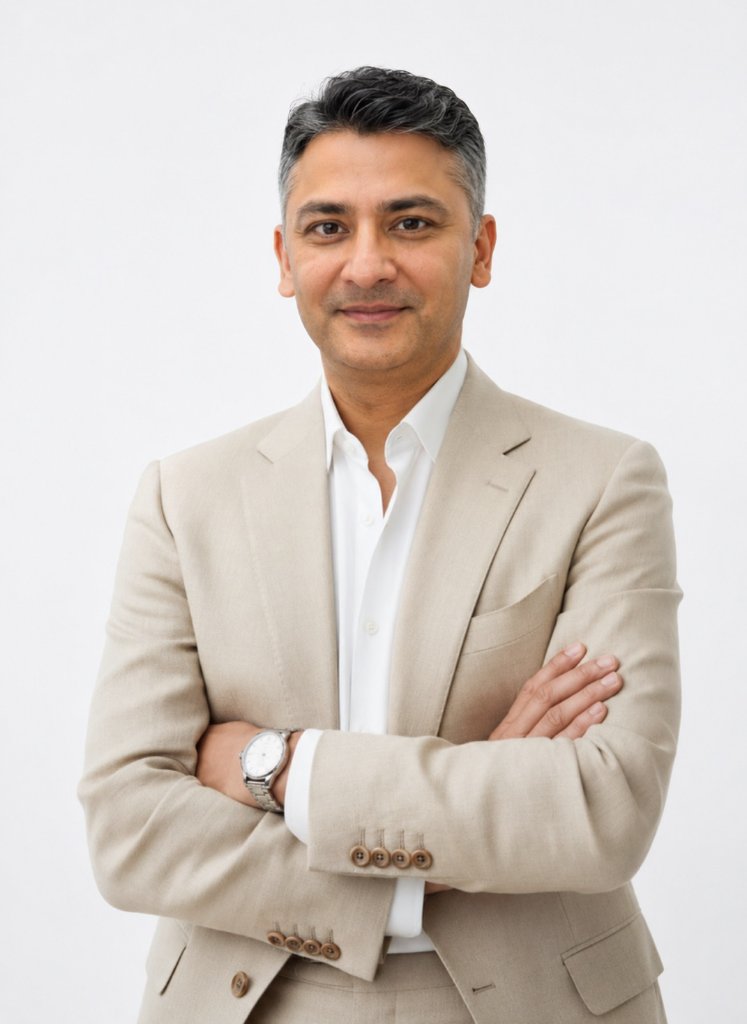
Dr. Aakash
Ramchand Dil
Published author, Official TEDx Speaker, Certified Fintech Expert™ (CFE), and Risk Management and Quantitative Finance Professional. Head of Market Risk and Capital Management at the National Bank of Fujairah, specialising in Market Risk, IFRS9 ECL, Stress Testing, BASEL Capital, and Credit Risk Modelling.
PhD (Mathematics) · DBA - Risk Management · CQF · Certified Fintech Expert™ (CFE) · TEDx Speaker · IIM Indore Alumni
24
Research Papers
32
Articles
7
Books Published
8
Citations
38
Milestones
PhD (Mathematics)
University of Hertfordshire, United Kingdom
DBA (Risk Management)
European International University, Paris
CQF — Paul Wilmott Scholar
CQF Institute, United Kingdom
Certified Fintech Expert™
Blockchain Council, June 2026
MBA with Merit
York Business School, United Kingdom (Lincoln Scholar)
Post Graduate Diploma Law (LLM)
Corporate Governance, University of Cumbria, United Kingdom
Associate Degree in Actuarial Science
Distinction in Bayesian Statistics, United Kingdom (2003–2006)
IIM Indore Alumni
First Pakistani to complete IIM — Strategic Financial Management for Executives, 2020
Profile
Executive / Head of Market Risk
& Capital Management
Dr. Aakash Ramchand Dil is an award-winning published author, Official TEDx Speaker, and a leading practitioner in Risk Management and Quantitative Finance. Currently serving as Executive / Unit Head of Market Risk, Quantitative Risks and Capital Management at the National Bank of Fujairah, Dubai, reporting directly to the Chief Risk Officer. Dr. Dil is also a Certified Fintech Expert™ (CFE) from Blockchain Council in California, USA.
A member of ALCO, Risk Committee, Investment Committee and Models Risk Committee, Dr. Dil has spearheaded landmark initiatives including IFRS9 implementation, Foundation IRB adoption, and single-handedly building the LGD model for the bank, recognised with the NBF Achievers Award and CEO's Certificate of Appreciation.
With over two decades of experience spanning Pakistan, Switzerland, and the UAE, he brings deep expertise across Market Risk, Credit Risk, Stress Testing, ICAAP, and Regulatory Capital, backed by a portfolio of 24 research papers, 7 books, and 6 published articles.
Specialisms
Recognition
Awards & Honours
Recipient of prestigious awards recognising excellence in risk management, quantitative finance, authorship, and banking analytics.
- 2026
CIO Views Cover Story — 10 Most Influential Leaders in Finance to Watch in 2026
CIO Views Magazine
- 2026
Beverly Hills Magazine Feature — Luxury Mindset of Leadership & Risk
Beverly Hills Magazine
- 2026
Global Excellence in Risk Management & Quantitative Finance Leadership Award
Elite Leadership Awards (ELA) 2026, DoubleTree by Hilton, Dubai
- 2026
Best Initiative in Risk Management of the Year
11th Middle East Banking and AI Analytics Summit
- 2025
Banking AI Tech Award 2025 — Excellence in Predictive Analysis for Banking
Middle East Banking AI & Analytics Summit / National Bank of Fujairah
- 2025
International Author Excellence Award 2025 Winner
Golden Awards Team
- 2018
NBF Achievers Award & CEO's Certificate of Appreciation
National Bank of Fujairah, Dubai, UAE
- 2015
Official Guinness World Record Attempt — Jenga & Chess
Guinness World Records
Recent Research Papers
2026
Methodologies for Calibrating and Backtesting Probability of Default Using Quarterly Default Rates in Line with Basel Guidelines
SSRN
2025
AI and Machine Learning in Credit Risk Assessment
SSRN
2026
Detailed Literature Review on Climate Risk adjusted Probability of Default (PD) for Credit Risk Modeling
SSRN
Latest Articles
The AI Writing Revolution: Are We Becoming More Productive or Less Authentic?
AI has quietly become one of the most influential writing assistants in history. But the real question is: what happens when we stop thinking and start outsourcing too much of our thinking to machines?
MAPE: Measuring Forecast Accuracy the Right Way
Few metrics are quoted as often and misunderstood as deeply as MAPE. This article breaks down what it is, how to calculate it, how to interpret it, and what goes wrong when it's misused.
Knowledge Series 24: An Intuitive Methodology to Check PD Sensitivity to Macroeconomic Variables
An intuitive, actionable methodology for checking PD sensitivity to macroeconomic variables — covering transmission channels, linkage mechanisms, stress testing, and strategic interpretation for IFRS 9/CECL compliance and proactive portfolio management.
Scholarly Impact
Work Cited
Peer-reviewed publications that have cited Dr. Dil's research in their methodology and reference lists.
Oil Shocks Fade, Equity Shocks Persist: Evidence from WTI Crude Oil and the S&P 500
AuthorsBharti Bharti
JournalCritical Letters in Economics & Finance, Vol. 3(2), Article 1
Pages
Published2026 · Technological University Dublin (ARROW@TU Dublin)
Cited Work
Testing for Time Series Stationarity: A Practical Guide to the Dickey-Fuller and Augmented Dickey-Fuller Tests
Cited in the reference list and methodology (ADF stationarity testing)
Comparison of ARCH and GARCH Models for Ethereum Return Volatility
AuthorsRizqi Akbar Makarim, Desinta Maheswari, Aqila Dina Pramustiwi, Kartika Ayu Rahmawati & Salma Fatila Ghaisani
Journalbit-Tech, Vol. 8(3)
Pages3099–3109
Published2026 · KDI (jurnal.kdi.or.id)
Cited Work
Testing for Time Series Stationarity: A Practical Guide to the Dickey-Fuller and Augmented Dickey-Fuller Tests
Cited in the reference list and literature review (time series stationarity testing)
Gated recurrent unit model for forecasting greenhouse gas concentrations with uncertainty quantification
AuthorsErica Hargety Kimei, Devotha Godfrey Nyambo, Neema Mduma & Shubi Felix Kaijage
JournalFrontiers in Artificial Intelligence, Vol. 9
Pages1782333
Published2026 · Frontiers Media SA
Cited Work
Testing for Time Series Stationarity: A Practical Guide to the Dickey-Fuller and Augmented Dickey-Fuller Tests
Cited in the reference list and methodology (time series stationarity testing)
Simulating the Interdependence Between Electricity Production and Water Release, Based on a Methodology that Combines Statistical Models and Artificial Intelligence
AuthorsHyllaa Anas Al-Omari, Najlaa Saad Ibrahim & Alla Abdul Alsattar Hamoodat
JournalStatistics, Optimization & Information Computing, Vol. 15(6)
Pages4757–4773
Published2026 · IAPress (International AcaPress)
Cited Work
Testing for Time Series Stationarity: A Practical Guide to the Dickey-Fuller and Augmented Dickey-Fuller Tests
Cited in the reference list and methodology (time series stationarity testing)
Impact of development and application of advanced technology on labor productivity and energy management efficiency in Vietnam
AuthorsThi Thu Huong Tran & Bich Ngoc Nguyen
JournalInternational Journal of Renewable Energy Development, Vol. 15(4)
Pages739–751
Published2026 · Center of Biomass and Renewable Energy (CBIORE)
Cited Work
Testing for Time Series Stationarity: A Practical Guide to the Dickey-Fuller and Augmented Dickey-Fuller Tests
Cited in the reference list and methodology (ADF / PP stationarity testing)
When Zero Defaults Mislead: A Power-Aware Validation Framework for Credit Risk Models
AuthorsYuxuan Huang
JournalSSRN Working Paper
Pages29 pp.
Published2026 · University of Nottingham
Cited Work
Methodologies to Develop Low Default Probability of Default Curve Models for the Portfolios with Zero Default Rates in-line with BASEL Requirements
Artificial Intelligence in Credit Risk Management: Current Practices, Systemic Implications, and Future Direction
AuthorsMir Md Moyazzem Hosen
JournalSSRN Working Paper
Pages21 pp.
Published2025 · UCLA / Bangladesh Bank
Cited Work
Dr. Aakash Ramchand Dil's research on credit risk management and AI/ML applications in risk modelling
Cited in the review of AI and machine learning applications in credit risk management
Buy-now-pay-later adoption: the interplay of approach and avoidance forces in attitude formation
AuthorsMahender Yadav, Brian Rutherford, Anjali Malik, Tanya Ranjan & Amit Kumar Singh
JournalJournal of Services Marketing, Vol. 40(4)
Pages519–534
Published2026 · Emerald Publishing Limited
Cited Work
AI and Machine Learning in Credit Risk Assessment
Cited in the reference list and literature review (AI/ML in credit risk assessment)
Latest Interview
In Conversation with
CityShift Finance
"Resilience, not speed, is becoming the new competitive advantage."
Dr. Dil discusses the convergence of uncertainty, AI's impact on market correlation, and the warning signs organizations identify too late.
Read the full interviewMedia
Videos & Podcasts
Watch talks, interviews and short-form content from Dr. Aakash Ramchand Dil.
View all media →Press Feature
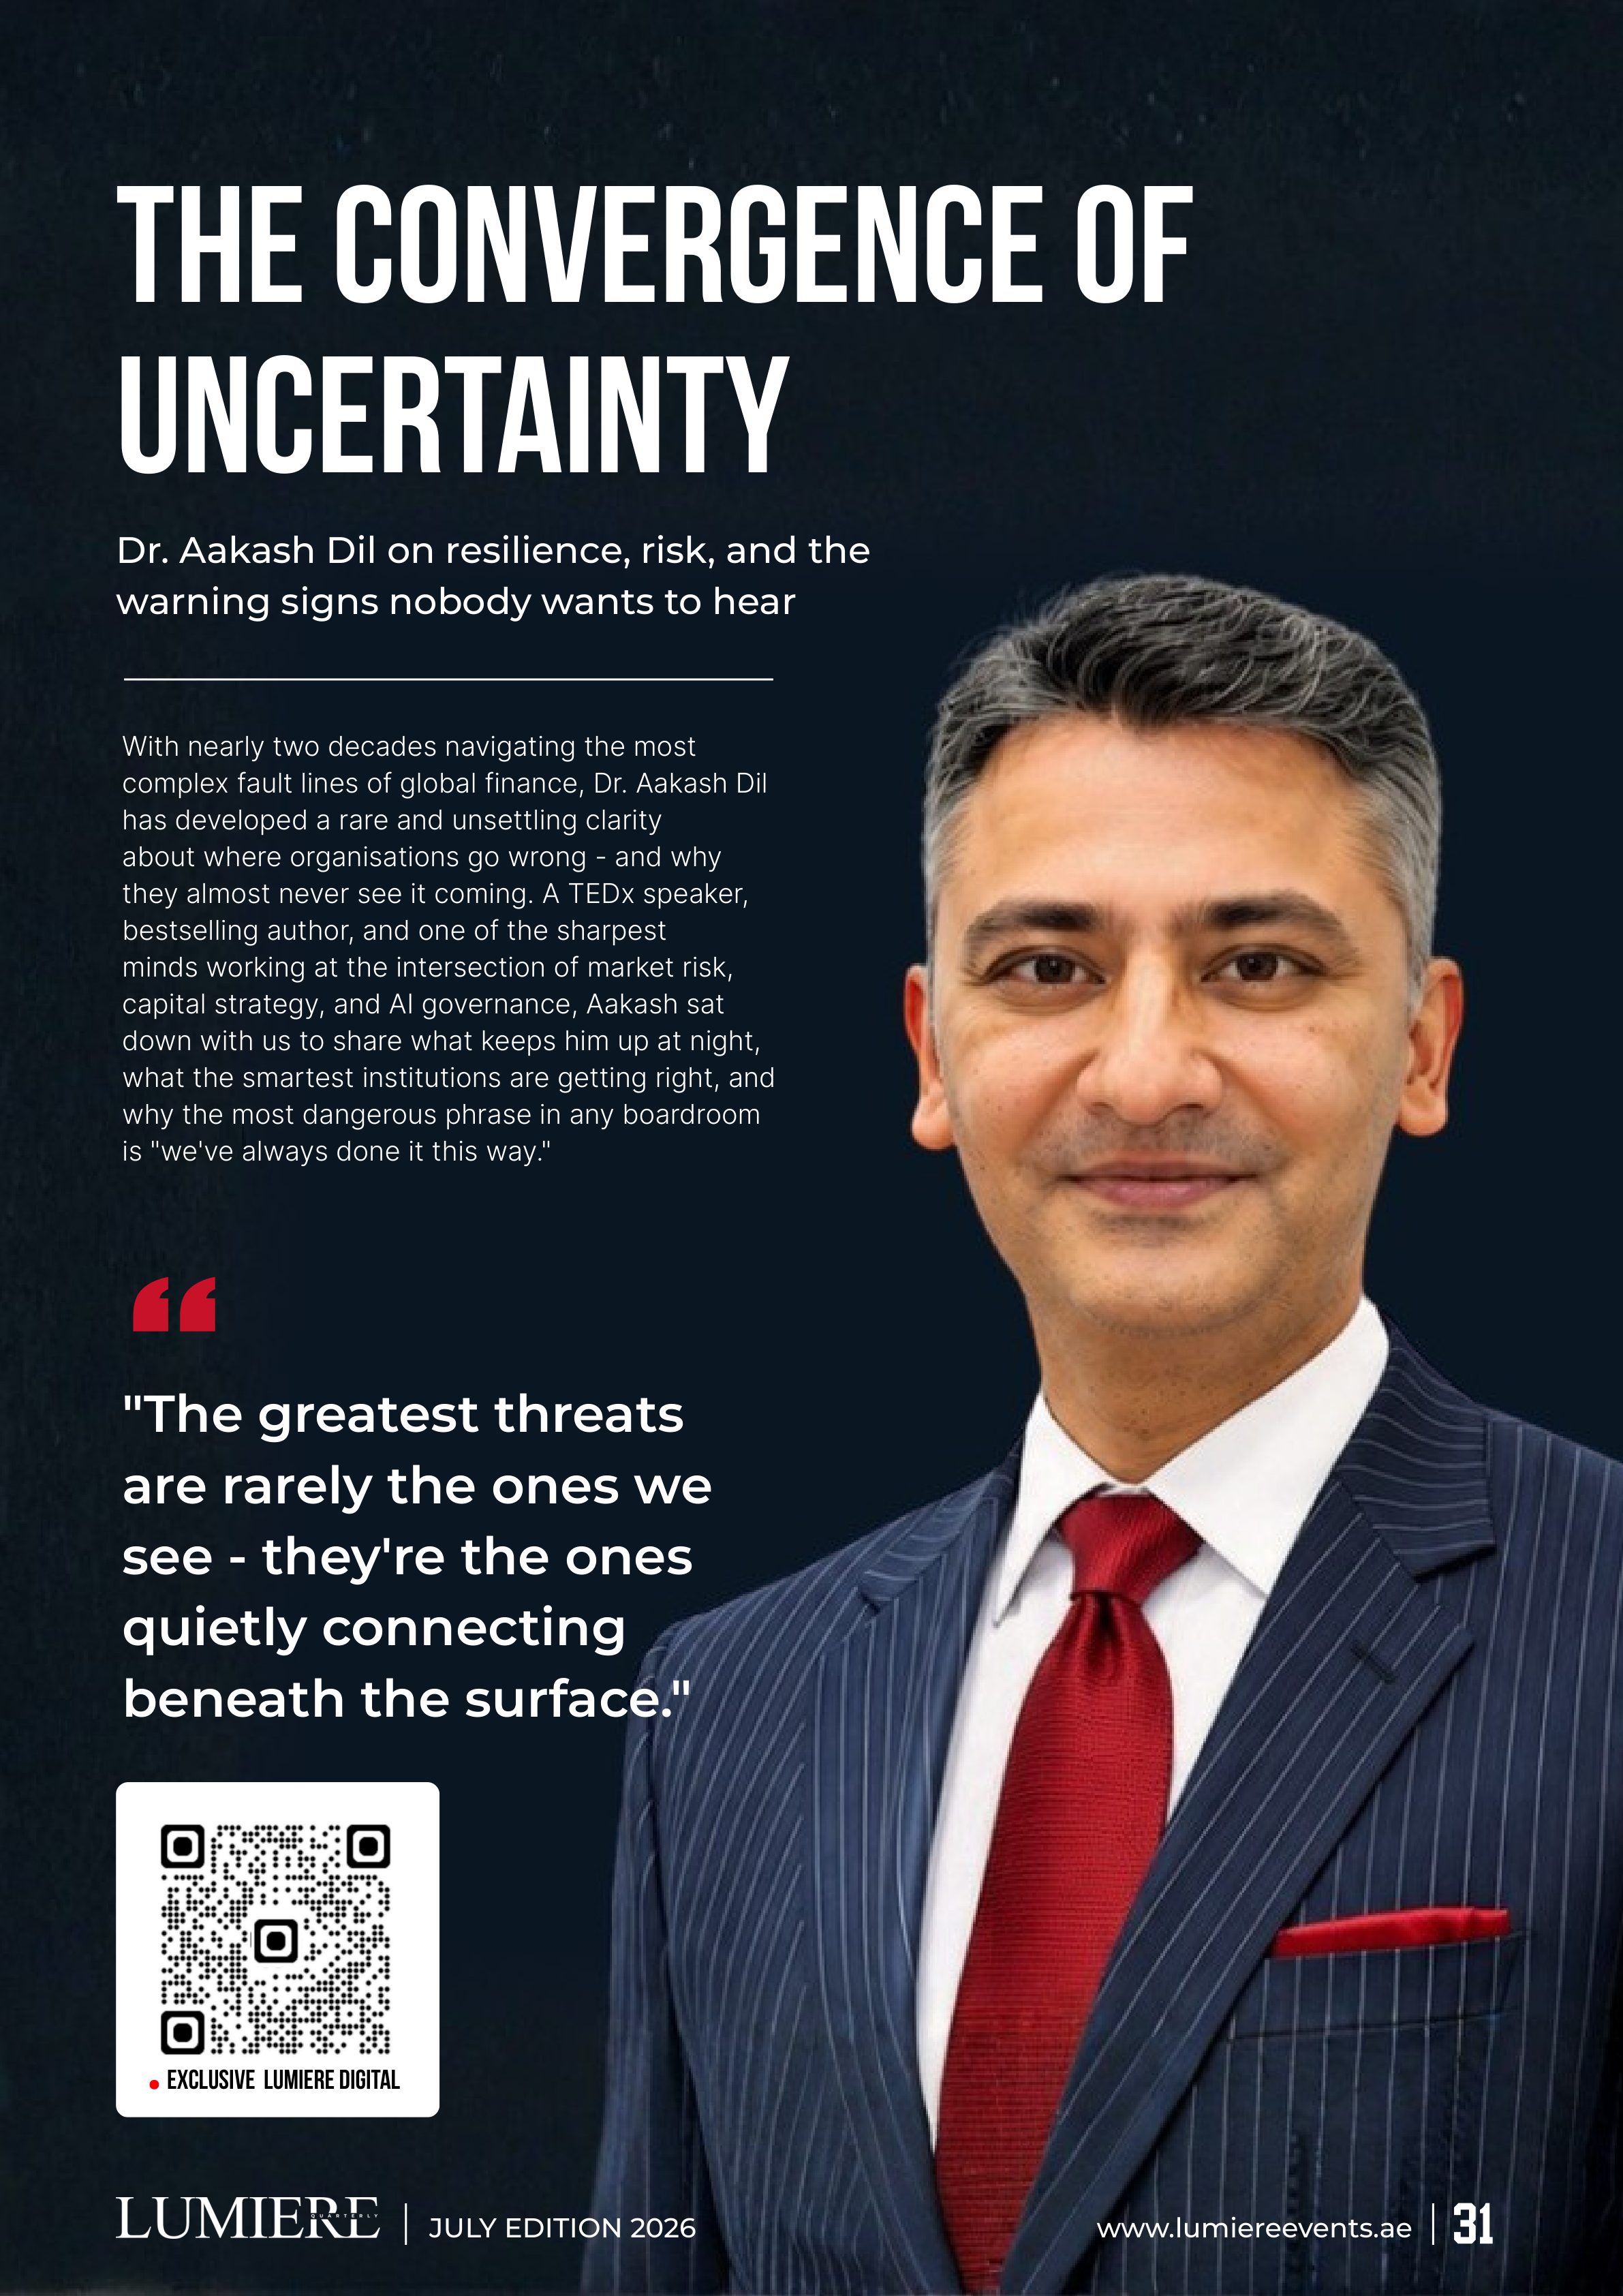
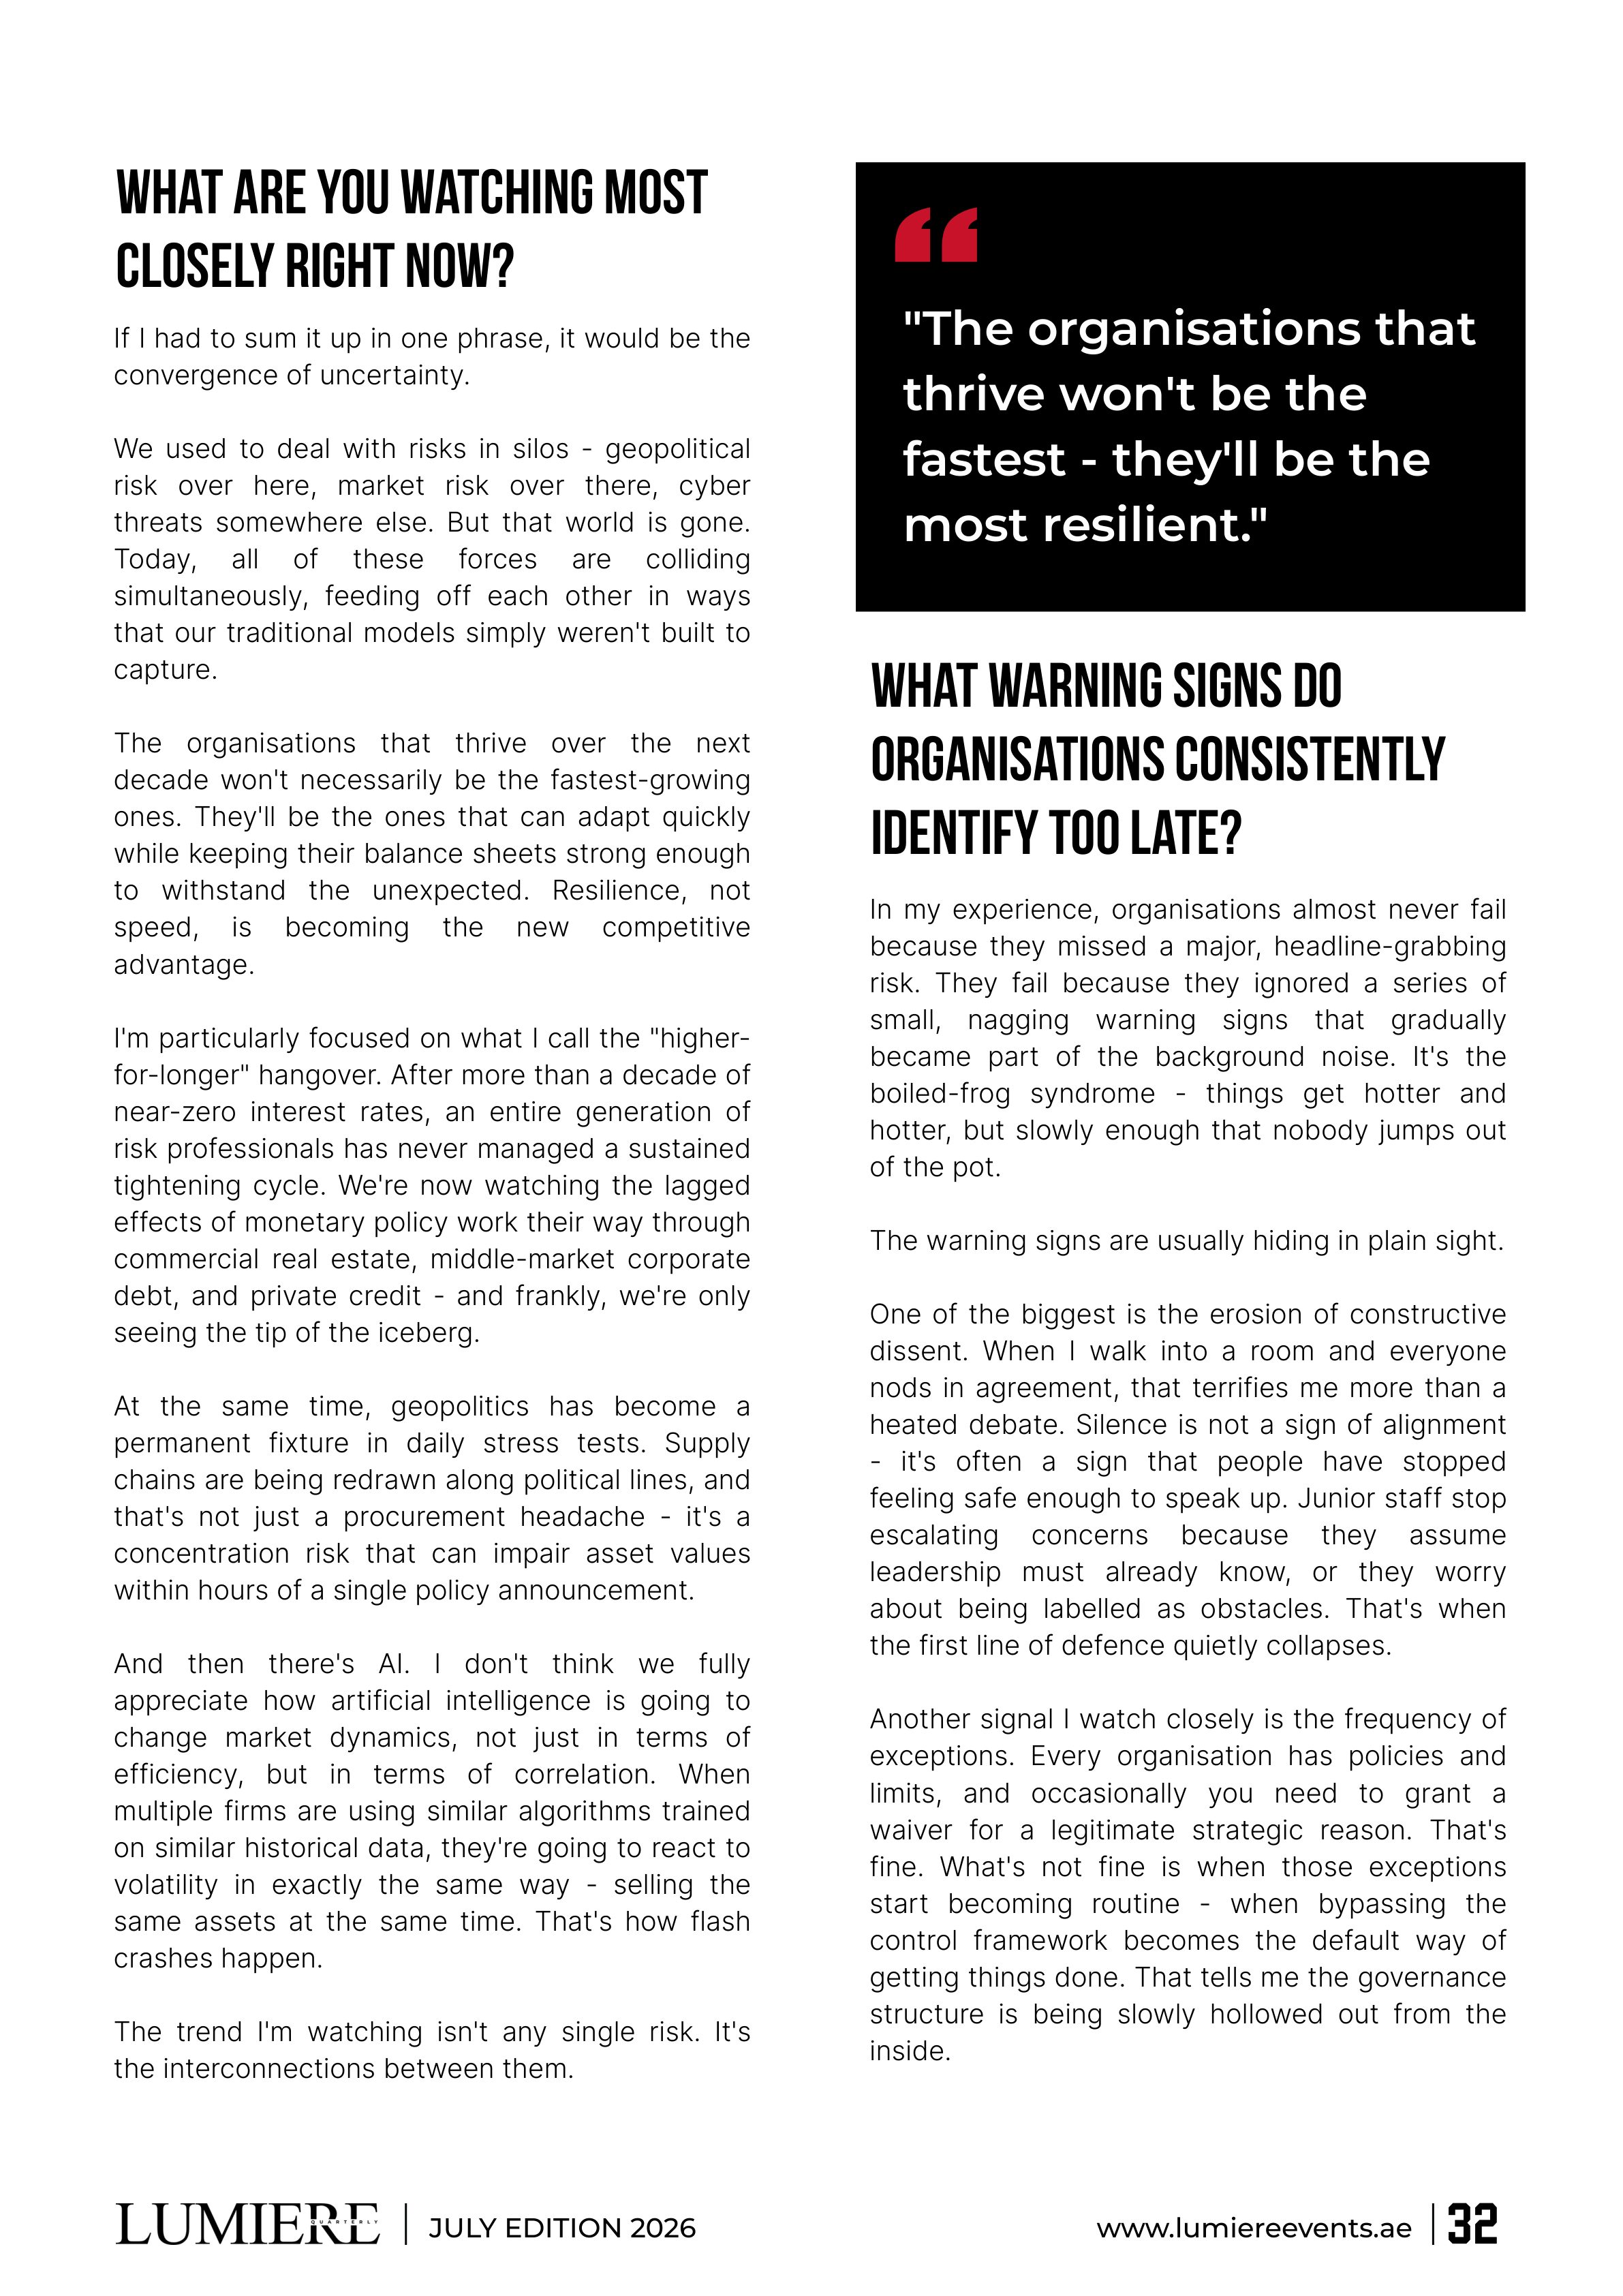
Featured in Lumière Magazine
A profile spotlight on Dr. Aakash Ramchand Dil — financial risk executive, quantitative finance expert, author, and double TEDx speaker. Preview the feature below and read the full magazine for the complete story.
Connect with me
Scan to save contact details and visit LinkedIn profile